After three decades watching deal cycles turn on capital availability and confidence, I've learned that when a major infrastructure contractor reaches for a $1.25 billion acquisition in an elevated-rate environment, it signals one of two things: either management sees structural tailwinds they're betting will outlast the macro headwinds, or they're locking in strategic assets before competition does. MasTec's (NYSE: MTZ) definitive agreement to acquire Murphy Corporation—one of the largest and most respected mechanical contractors in the United States—suggests the former. This is not a desperate fire-sale grab; it's a calculated move into mission-critical end markets at a moment when most of Wall Street is still waiting for the Fed to blink.
The sheer longevity of Murphy—founded in 1907—tells you something about the durability of the mechanical contracting business. A 120-year-old shop doesn't survive by chasing fads. It survives by building indispensable relationships in infrastructure, industrial, and mission-critical facilities where downtime is not an option. For MasTec, which already operates across engineering, procurement, and construction (EPC) services, adding Murphy's deep mechanical expertise and customer base could reshape how the company competes for large, complex projects in data centers, manufacturing plants, and critical infrastructure. The transaction is structured as a definitive agreement, meaning both parties have committed to the deal, though regulatory and customary closing conditions remain.
Why Mission-Critical Matters in This Cycle
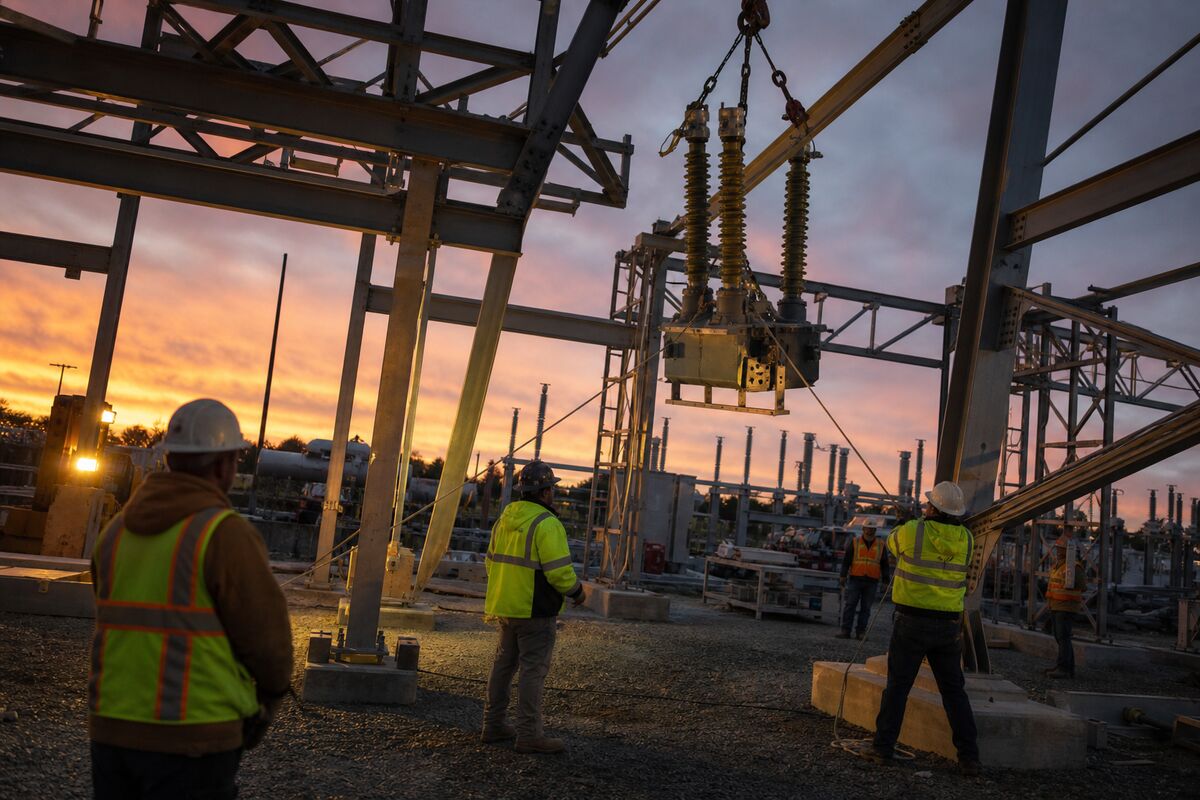
Let's be clear about what "mission-critical" means in the infrastructure and industrial world. These are facilities and systems that cannot afford interruption—data centers that power cloud services, semiconductor fabs that can't tolerate a single hour of downtime, power generation and distribution networks, hospitals, and specialized manufacturing. When you're a mechanical contractor serving those markets, your customer base has pricing power and a structural need for your services that transcends the business cycle.
Murphy's exposure to these end markets is precisely what makes this acquisition strategically valuable to MasTec. In a period when traditional construction spending can wobble with interest rates and sentiment, mission-critical work has proven more resilient. The data center boom alone—driven by artificial intelligence infrastructure investment—has created a multi-year tailwind for mechanical contractors capable of handling complex HVAC, piping, and systems integration at scale. By absorbing Murphy's customer relationships, technical capabilities, and backlog, MasTec could be positioning itself to capture a larger share of this structural demand.
What the Deal Signals About Backlog and Growth
For traders and investors monitoring MasTec, the key question is straightforward: what does Murphy's backlog look like, and how does it change MTZ's forward revenue visibility? The sources confirm the acquisition's strategic rationale—mission-critical exposure and expanded infrastructure reach—but the real market impact will depend on the quality and duration of Murphy's contracted work. A mechanical contractor with a robust, multi-year backlog in high-margin end markets could materially lift MasTec's earnings trajectory. Conversely, if Murphy's backlog is thin or heavily weighted to near-term completion, the $1.25 billion price tag may warrant closer scrutiny on valuation and return on capital.
This is where the distinction between a definitive agreement and a closed deal matters. Right now, MasTec and Murphy have committed to the transaction, but it has not closed. That means there's still time for both parties to finalize due diligence, secure any required regulatory approvals, and confirm the financial details that will ultimately determine whether this deal creates shareholder value or destroys it. Investors will be watching for any subsequent disclosures on financing sources, integration plans, and expected synergies—information that often trickles out in conference calls and SEC filings in the weeks and months ahead.
The Broader M&A Message: Infrastructure Conviction Despite Rate Headwinds
What's perhaps most interesting about this deal is the message it sends to the broader market. We're still in a period of elevated interest rates. Refinancing costs for large acquisitions remain meaningful. Yet MasTec, a company with significant exposure to infrastructure and industrial projects, is willing to deploy $1.25 billion in cash or debt to acquire a mechanical contractor. That's a vote of confidence—not in the macro environment, but in the structural demand for infrastructure and industrial services over the next several years.
It also suggests that large, well-capitalized players in the engineering and construction space are consolidating. Smaller, specialized contractors like Murphy may face pressure to merge with or be acquired by larger platforms that can offer capital, scale, and cross-selling opportunities. For MasTec, the acquisition is a way to broaden its service offerings and deepen its relationships in markets where it already competes. For Murphy shareholders, it's a liquidity event that values the company at a price both sides have agreed reflects its future prospects.
Near-Term Watch Items for MTZ Shares
Traders should keep their eyes on several developments as this deal progresses toward closing. First, the market's immediate reaction to the $1.25 billion price tag will matter. If investors view it as a reasonable premium for Murphy's assets and backlog, MTZ shares may find support. If the market sees it as expensive, expect volatility. Second, watch for any guidance updates or commentary from MasTec management on integration timelines and expected synergies. Large acquisitions often promise cost savings, revenue synergies, or margin expansion—but delivery on those promises is where the real value creation (or destruction) happens.
Third, monitor the closing timeline and any conditions that could delay or derail the transaction. While both parties have signed a definitive agreement, deals can still fall apart if due diligence uncovers issues, financing dries up, or regulatory hurdles emerge. For a mechanical contractor of Murphy's size and scope, antitrust review is unlikely to be a major issue, but it's worth tracking. Fourth, keep an eye on MasTec's balance sheet and liquidity. A $1.25 billion acquisition will have implications for debt levels, credit ratings, and capital allocation priorities. Management will need to articulate how the company plans to finance the deal and maintain financial flexibility for other investments or shareholder returns.
The Bigger Picture: Infrastructure and Industrial Demand Remains Intact
At the highest level, this deal reflects a simple reality: infrastructure and industrial construction demand remains robust, even in an uncertain macro environment. The Biden administration's infrastructure investments, the reshoring of manufacturing, and the data center buildout are all structural forces that transcend any single business cycle. For a contractor like MasTec with the scale and capital to execute large, complex projects, acquiring a specialist like Murphy is a rational move to capture more of that demand and improve competitive positioning.
Whether the $1.25 billion price tag proves to be a bargain or a misstep will depend on Murphy's backlog quality, the success of integration, and the broader trajectory of infrastructure spending over the next 3–5 years. For now, MasTec has placed its bet. The market will ultimately judge whether it was the right call.
Bull/Bear Verdict
Bull Case: MasTec's $1.25 billion acquisition of Murphy Corporation could significantly expand the company's exposure to mission-critical end markets—data centers, semiconductor fabs, and specialized manufacturing—where structural demand remains robust despite elevated interest rates. Murphy's 120-year operating history and customer base suggest durable backlog and pricing power, potentially lifting MTZ's forward revenue visibility and margin profile. The deal signals management confidence in infrastructure and industrial demand tailwinds, which may resonate with investors betting on continued capital deployment in these sectors.
Bear Case: At $1.25 billion, the acquisition price could be rich if Murphy's backlog is thin or near-term weighted, raising questions about return on capital and integration execution risk. Large acquisitions in elevated-rate environments carry financing costs and balance-sheet strain; MasTec will need to articulate clear synergies and a credible integration plan to justify the outlay. Regulatory approval and closing conditions remain, and any deterioration in infrastructure spending or mission-critical demand could undermine the deal's strategic rationale and MTZ's ability to generate shareholder value from the transaction.