Energy consolidation is no longer a background theme—it is becoming the trade. Diamondback Energy’s confirmation of a $5 billion acquisition of Permian Basin holdings from Double Eagle puts $FANG at the center of that shift and gives energy traders a fresh catalyst to monitor.
The transaction matters beyond the headline value. It arrives as oil prices soften and as consolidation across the energy sector accelerates, creating a direct test of how investors value scale, inventory and deal-making discipline. The market implication is clear: Diamondback is using a major transaction to strengthen its Permian position, while traders are now looking for signs of whether the deal can support continued interest in $FANG and expand the search for potential M&A premium opportunities across the sector.
Diamondback confirmed the deal on November 16, 2026, acquiring Permian Basin holdings from Double Eagle for $5 billion. The reported transaction is the central fact, but its significance rests in the timing. When oil prices are softening, energy companies face a more demanding operating environment. A large land acquisition under those conditions can signal that management sees strategic value in consolidation even when commodity-market sentiment is less supportive.
That does not automatically make the transaction bullish for the stock. It does, however, create a substantial event for traders to evaluate. The market will weigh the scale of the assets against the financial and strategic commitments implied by a cash-and-stock-style land deal. The structure matters because it frames how the acquisition may affect shareholder exposure, capital allocation and the market’s assessment of Diamondback’s willingness to pursue growth through consolidation.
Why the Permian remains the battleground
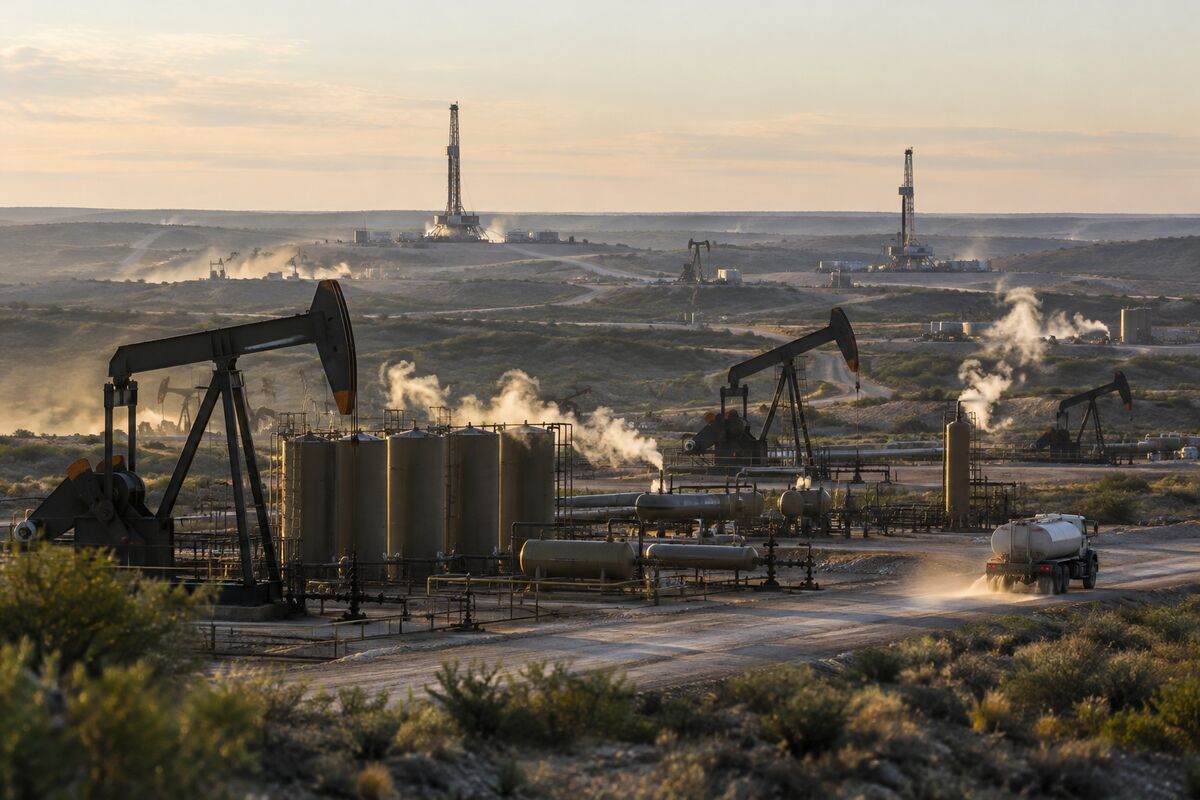
The Permian Basin holdings acquired from Double Eagle give this transaction a clear strategic focus. This is not an abstract corporate combination. It is a deal centered on a major North American energy region, making the acquisition relevant to traders tracking how producers assemble positions in established operating areas.
For Diamondback, the $5 billion price tag places the company’s acquisition strategy firmly in view. The transaction may be read as an attempt to build greater scale in the Permian and reinforce the value of an integrated land position. For the broader sector, it offers another indication that energy companies may pursue consolidation even as oil prices become less favorable.
That combination—softening oil prices and continued deal activity—is what makes the announcement particularly important. In a stronger commodity environment, acquisitions can be dismissed as straightforward expansion. In a softer environment, a large deal raises a sharper question: are companies buying because assets are becoming more strategically attractive, or because management teams believe scale will matter more as the cycle becomes tougher?
The answer is not established by the announcement alone. Traders will therefore focus on the market’s interpretation rather than simply the transaction’s size. A $5 billion acquisition can be viewed as a vote of confidence in the Permian, a consolidation move designed to improve scale, or a test of whether deal-making can create shareholder value while commodity prices are under pressure.
What $FANG traders may watch next
The immediate trading focus is likely to remain on whether Diamondback’s announcement becomes a catalyst for continued attention in $FANG. The relevant question is not whether the deal guarantees a breakout continuation—it does not—but whether the transaction changes the stock’s narrative enough to sustain momentum if traders were already positioning around the company’s strategic profile.
That makes the next phase about confirmation. Traders may watch how $FANG responds to the deal’s strategic message, how the market assesses the $5 billion commitment and whether the acquisition strengthens confidence in Diamondback’s position within the Permian. The stock’s reaction will help determine whether the transaction is treated as a constructive consolidation event or as a capital-allocation decision requiring greater scrutiny.
The cash-and-stock-style structure will also remain important to that analysis. A deal using more than one form of consideration can influence how shareholders view the balance between immediate funding requirements and equity participation. Without moving beyond the reported facts, the structure gives traders another lens through which to examine the transaction’s potential impact on Diamondback’s capital position and shareholder alignment.
A signal for the wider energy M&A market
Diamondback’s deal also raises the stakes for other energy-sector companies that may be viewed as potential consolidation candidates. The announcement does not identify additional targets, and it does not establish that another transaction is imminent. What it does provide is a market reference point: a $5 billion Permian acquisition confirmed while oil prices soften.
That reference point may shape how traders assess M&A premium opportunities elsewhere in the sector. Companies with meaningful land positions could attract renewed attention if investors believe scale is becoming more valuable. Meanwhile, potential acquirers may face greater scrutiny over whether transactions are strategically coherent and appropriately structured.
This is where the trader-focused opportunity—and risk—sits. M&A speculation can move quickly, but the confirmed facts are limited to Diamondback’s acquisition of Double Eagle’s Permian holdings. The broader consolidation theme is credible as a market framework, yet individual companies should not be treated as transaction candidates without a reported deal or explicit announcement.
The more durable conclusion is that energy consolidation is becoming a central market narrative on November 16, 2026. Diamondback has supplied the clearest data point: a confirmed $5 billion transaction in the Permian. Traders now have a concrete event against which to measure the sector’s appetite for scale, the market’s tolerance for cash-and-stock-style deals and the potential for further consolidation as oil prices soften.
For $FANG, the deal creates a potentially important catalyst, but its ultimate market impact will depend on how investors interpret the acquisition. For the wider energy sector, it signals that M&A may remain an active source of volatility and valuation debate. The disciplined approach is to separate the confirmed transaction from speculation about what comes next—a distinction that matters whenever consolidation becomes the trade.
Read the reported confirmation of Diamondback Energy’s $5 billion acquisition from Double Eagle for the transaction details underlying this analysis.
Bull/Bear Verdict
Bull Case: The confirmed $5 billion acquisition of Permian Basin holdings may strengthen Diamondback’s strategic scale and position $FANG as a leading catalyst in an accelerating energy-consolidation cycle.
Bear Case: Softening oil prices could make the $5 billion commitment more demanding for shareholders, while the cash-and-stock-style structure may keep traders focused on capital allocation and execution risk.