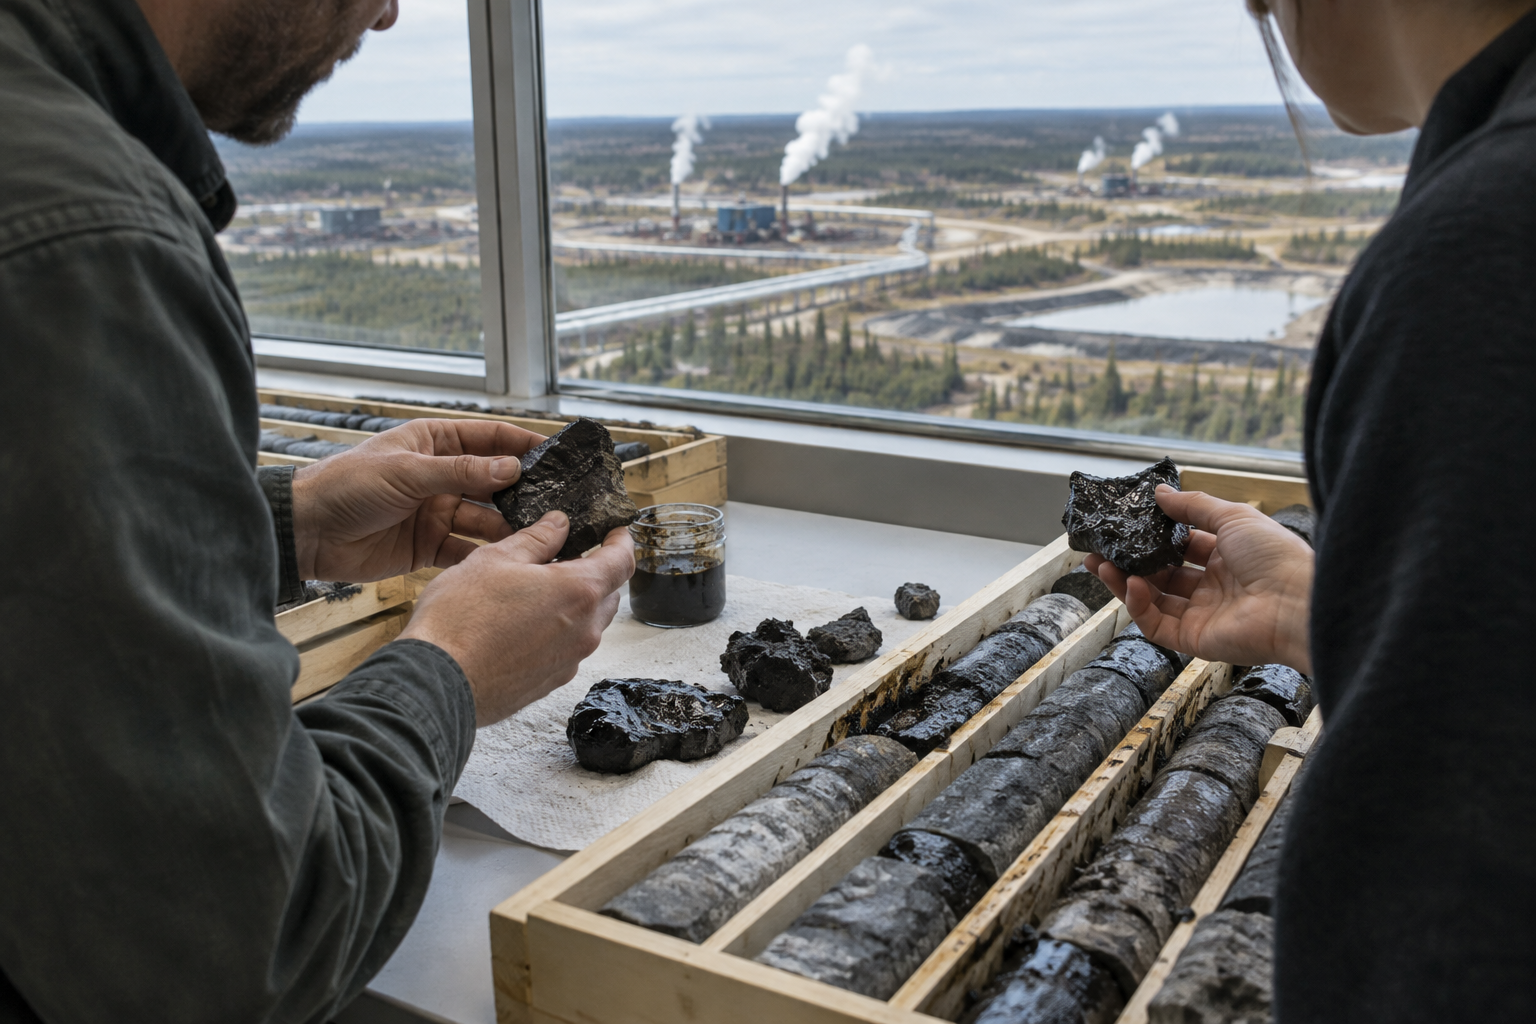
A $5.7 billion oil-sands transaction has put Canadian energy consolidation back on the trading screen. Cenovus Energy Inc. has entered a definitive arrangement agreement to acquire Athabasca Oil Corporation in a cash-and-stock deal, creating a new test for merger arbitrage traders and a strategic question for the broader sector.
The immediate issue is not simply whether the combination makes industrial sense. It is how the market prices Athabasca's cash-and-stock consideration, and how investors assess what the transaction could mean for Cenovus's financing profile and share dilution. That tension may define the first phase of trading in both names.
The deal mechanics traders will watch
Cenovus trades as $CVE on both the Toronto Stock Exchange and the New York Stock Exchange. Athabasca trades as $ATH on the TSX. The companies announced the transaction separately on October 5, 2026, with Cenovus describing the agreement as an acquisition carrying an implied enterprise value of $5.7 billion.
Because the consideration combines cash and Cenovus stock, Athabasca's market value may not immediately track the headline transaction value. That structure can create an arbitrage spread: the gap between the implied value of the consideration and the price at which Athabasca shares trade while the deal moves through its process. The size and persistence of that spread would depend on market expectations, but the supplied announcements do not provide an exchange ratio, offer premium or share-price data—and those figures should not be inferred.
For traders, the key point is straightforward. $ATH becomes a transaction-linked security whose valuation may reflect both the cash component and the market value of the Cenovus shares included in the consideration. Meanwhile, $CVE becomes the financing and dilution vehicle for the deal. That may leave the market focused on how Cenovus funds the transaction and whether issuing stock changes the per-share economics for existing shareholders.
The companies' confirming releases are available through Cenovus's announcement and Athabasca's announcement. Those releases establish the transaction and its structure; they do not justify adding unconfirmed deal terms or a view on where either stock should trade.
Why Cenovus's reaction matters
With no supplied share-price data, it would be premature to characterize the market's reaction as positive or negative. The more useful question is what investors may measure next. For Cenovus, attention could center on deal financing, the scale of any equity component and the potential dilution concern that naturally accompanies a cash-and-stock acquisition.
That creates a familiar market contrast. Athabasca may trade around the perceived value of the consideration, while Cenovus may be judged on whether the acquisition strengthens its operating position without placing too much weight on financing or dilution. The two stocks therefore offer different expressions of the same event: transaction certainty and spread analysis for $ATH, capital-allocation scrutiny for $CVE.
A signal for Canadian oil sands consolidation
The strategic implication extends beyond the two tickers. A transaction with an implied enterprise value of $5.7 billion could reinforce the view that Canadian oil-sands assets remain candidates for consolidation. Larger operators may seek scale, operational integration or a broader resource base, while smaller producers may face greater scrutiny over their standalone position.
Still, one announced deal does not establish a sector-wide wave. The next phase will depend on how the market evaluates this agreement and whether the transaction changes expectations for additional combinations. Energy-sector sentiment may also be tested as companies approach the fourth-quarter earnings season. Investors could compare management commentary on capital allocation, balance-sheet discipline and consolidation with the benchmark created by Cenovus's agreement to acquire Athabasca.
The bottom line: this is both a corporate combination and a live market-structure event. The cash-and-stock format puts an arbitrage spread around $ATH and places financing and dilution questions around $CVE. Until more specific transaction terms or market data are confirmed, discipline matters more than dramatic conclusions.
Bull/Bear Verdict
Bull Case: The $5.7 billion implied enterprise value could strengthen the strategic consolidation case for Canadian oil sands, while the cash-and-stock structure may create a defined arbitrage framework around $ATH.
Bear Case: The same structure may keep pressure on $CVE if traders focus on deal financing and potential dilution, while the absence of confirmed exchange ratios or premiums leaves the $ATH spread difficult to quantify.